
Property investment in Marrakech
Kasbah Nelaria in Marrakech and the returns of a 10-suite boutique hotel
A five-year simulation and the conditions for targeting more than 20%
Can a ten-suite boutique hotel in Marrakech target an annual balance exceeding 20% of its acquisition price? In the simulation presented here, that threshold is crossed in year three: €538,370 against a reference price of €2,000,000, or 26.9%. This projected ratio relies on an ambitious commercial scenario. It is neither a guaranteed net return nor a return calculated on the total investment cost.
The Kasbah Nelaria & Spa concept helps explain this approach: ten suites, a Berber Chic identity, accommodation income and complementary activities. The aim is to create a distinctive property asset and a hospitality business capable of developing its customer base and reputation.
Discover the Kasbah Nelaria & Spa project
What this simulation measures
This case study details a scenario over five operating years. Year 1 means the model’s first year of activity, rather than the calendar year 2026. The figures are simulation assumptions; they do not describe results already achieved and do not replace the project’s updated financial dossier.
The tables add together room receipts after deductions, additional sales and the contribution margins from the spa, restaurant and packages. The resulting total is an economic aggregate within the model, rather than accounting revenue. Costs already deducted from each margin must be reconciled with shared expenses to avoid double counting.
The final balance takes account of the expenses and fees shown. The model does not demonstrate full inclusion of depreciation, taxes, financing, replacement investment and all cash requirements. This is why we use the term “simulation balance after management fees”.
A place to stay with several business activities
Rooms form the foundation of the operation. The spa and restaurant can complement this activity. Transfers, excursions and experiences enrich the stay. Packages combine several services in a commercial offer; their additional contribution must not be counted twice.
This case study complements our investment guides. Its purpose is to show the mechanisms and conditions of a specific scenario, rather than suggest an average return for all boutique hotels in Marrakech.
How much the ten suites could generate
A ten-suite property open 365 days has 3,650 available room nights per year. Gross room revenue excluding tax is calculated as follows: 10 × 365 × occupancy rate × ADR excluding tax. ADR is the average rate actually achieved per room sold, using a consistent convention.
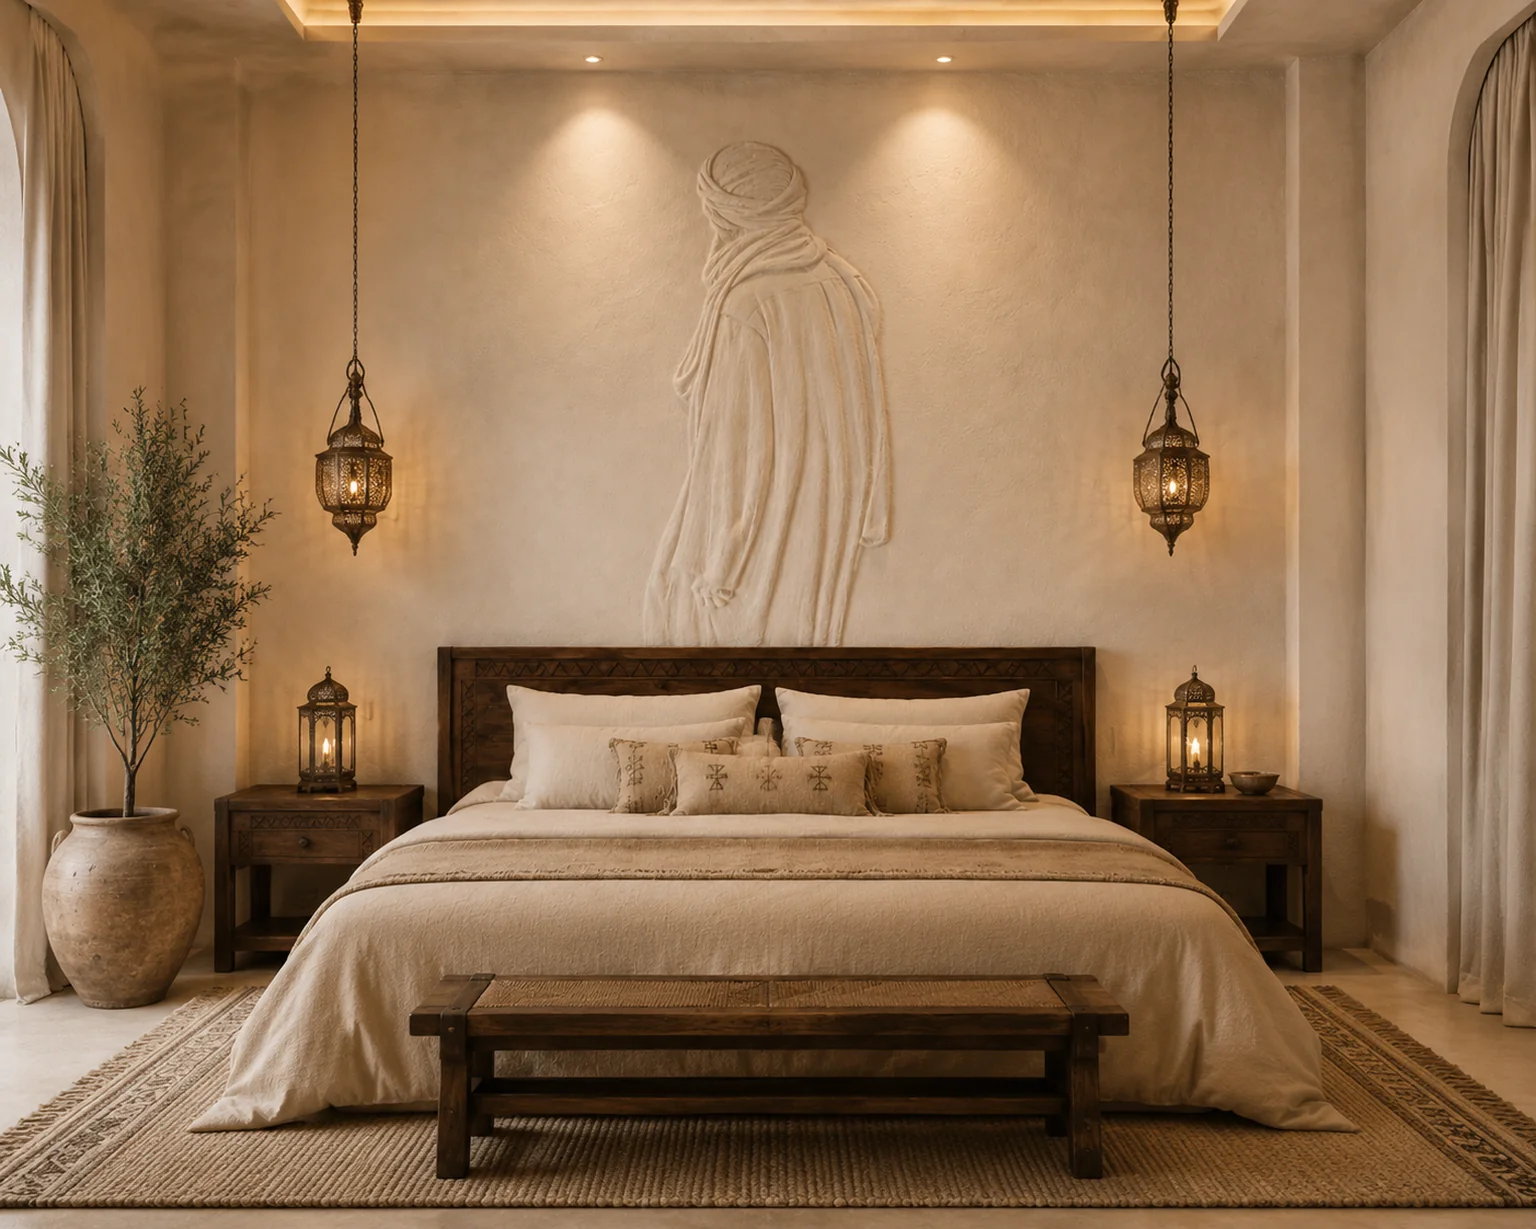
Official architectural rendering of Kasbah Nelaria & Spa — room Aylan
| Indicator | Year 1 | Year 2 | Year 3 | Year 4 | Year 5 |
|---|---|---|---|---|---|
| ADR excluding tax | 150 € | 200 € | 250 € | 300 € | 325 € |
| Occupancy | 75% | 80% | 85% | 87.5% | 90% |
| Gross room revenue excluding tax | 410,625 € | 584,000 € | 775,625 € | 958,125 € | 1,067,625 € |
| Receipts after deductions | 352,458 € | 513,209 € | 692,876 € | 857,372 € | 952,831 € |
| Model deductions | 58,167 € | 70,791 € | 82,749 € | 100,753 € | 114,794 € |
Deductions represent approximately 14.17% of gross revenue in year 1 and 10.75% in year 5. This implicit rate cannot automatically be equated with an OTA commission: the share sold through each channel, commissions and other adjustments must be identified. A discount already reflected in ADR must not be deducted a second time.
Moving from €150 to €325 in ADR and from 75% to 90% occupancy describes particularly strong growth. It requires consistent product and service quality, a solid reputation and effective marketing. These figures are scenario targets, rather than established market benchmarks.
Complementary income and contributions
| Item | Year 1 | Year 2 | Year 3 | Year 4 | Year 5 |
|---|---|---|---|---|---|
| Room receipts after deductions | 352,458 € | 513,209 € | 692,876 € | 857,372 € | 952,831 € |
| Additional sales | 40,160 € | 64,230 € | 91,000 € | 117,100 € | 144,540 € |
| Package margin | 3,000 € | 6,000 € | 9,000 € | 12,000 € | 15,000 € |
| Spa margin | 118,625 € | 142,350 € | 166,075 € | 189,800 € | 213,525 € |
| Restaurant margin | 47,450 € | 71,175 € | 94,900 € | 118,625 € | 142,350 € |
| Economic total | 561,693 € | 796,964 € | 1,053,851 € | 1,294,897 € | 1,468,246 € |
Additional sales must be matched to the costs of delivering them: transport, service providers and any commissions. For the spa and restaurant, service volumes, average spend and direct costs must explain the margin used. Meals, treatments and room nights included in packages must be allocated between activities; only a genuinely additional contribution can be added.
What expense budget for ten suites
The property must fund its teams, equipment and services. The initial budget used in the simulation amounts to €21,850 per month, or €262,200 per year.
| Item | Monthly | Annual |
|---|---|---|
| Salaries | 9,000 € | 108,000 € |
| Social contribution provision | 2,700 € | 32,400 € |
| Water | 1,000 € | 12,000 € |
| Electricity | 1,000 € | 12,000 € |
| Food and meals | 3,000 € | 36,000 € |
| Accountant | 250 € | 3,000 € |
| Linen | 100 € | 1,200 € |
| Connectivity | 300 € | 3,600 € |
| Maintenance and contingencies | 1,500 € | 18,000 € |
| Communication and advertising | 3,000 € | 36,000 € |
| Total | 21,850 € | 262,200 € |
The social contribution provision represents 30% of the payroll budget in this model. This percentage is a budgeting assumption and does not assert a uniform statutory rate. The staffing structure must cover reception hours, housekeeping, cooking, service and wellness treatments.
The “linen” item must be precisely defined. At 75% occupancy, its €1,200 annual budget represents approximately €0.44 per occupied room night. If it covers replacement only, laundry costs must be identified elsewhere. Food purchases must likewise be reconciled with costs already deducted from the restaurant margin.
Insurance, payment fees, management software, consumables, furniture replacement and launch costs must be assigned to an explicit item or added if they are not included. An expense included in an activity’s margin must not be deducted again from shared expenses.
Why expenses increase by ten per cent
The scenario applies a 10% annual increase to the expenses shown: €262,200, then €288,420, €317,262, €348,988 and €383,887. This progression is a simulation convention, rather than a general inflation forecast.
Over the same period, gross room revenue increases by 160%, while the expenses shown rise by 46.4%. To assess this operating leverage, fixed costs, variable costs and costs already deducted from spa and restaurant contributions must be separated. A monthly forecast will also help measure low-season cash requirements.
What balance remains after management fees
The fees shown can be reconstructed, subject to rounding, using 25% of the sum of room receipts after deductions, additional sales and the package margin. This is the calculation base used to interpret this simulation; it does not replace the contractual definition of services, the fee base and applicable taxes.
Example in year 3: (€692,876 + €91,000 + €9,000) × 25% = €198,219. Spa and restaurant margins are not included in this reconstructed fee base. Their treatment must be confirmed in the relevant contract.
| Indicator | Year 1 | Year 2 | Year 3 | Year 4 | Year 5 |
|---|---|---|---|---|---|
| Economic total | 561,693 € | 796,964 € | 1,053,851 € | 1,294,897 € | 1,468,246 € |
| Expenses shown | 262,200 € | 288,420 € | 317,262 € | 348,988 € | 383,887 € |
| Balance before management fees | 299,493 € | 508,544 € | 736,589 € | 945,909 € | 1,084,359 € |
| Rounded fees | 98,905 € | 145,860 € | 198,219 € | 246,618 € | 278,093 € |
| Balance after management fees | 200,588 € | 362,684 € | 538,370 € | 699,291 € | 806,266 € |
| Ratio on €2.3m | 10.0% | 18.1% | 26.9% | 35.0% | 40.3% |
The amounts in the table are rounded to the nearest euro. The cumulative balances shown total €2,607,199 over five years. This does not demonstrate recovery of the capital: the cash flows actually available after tax, financing, equipment replacement and other excluded expenditure must still be established.
Under what conditions the twenty per cent threshold is crossed
A 20% ratio on €2,000,000 represents €400,000 per year. In this scenario, the balance after management fees exceeds that amount in year three. However, the price “from €2,000,000” must be distinguished from the total cost of the operation: fees, any excluded equipment and start-up working capital must be specified in the investment dossier.
For illustration, with total capital of €2.55 million rather than €2,000,000, the same year-3 balance would represent 21.1%. This is an arithmetic sensitivity example, rather than an estimate of Kasbah Nelaria’s actual budget.
What happens if occupancy falls
At an ADR of €300, ten percentage points of occupancy represent €109,500 in annual gross room revenue. For illustration, an ADR of €250 and 65% occupancy produce €593,125 in gross room revenue; €275 and 75% produce approximately €752,813, compared with €958,125 at €300 and 87.5%. These examples isolate accommodation and are not profit forecasts. Each scenario requires commissions, complementary activities and variable costs to be recalculated.
The existing simulator uses different expenses and a different management formula from the tables in this article. Its results are therefore not directly comparable. View the Kasbah Nelaria simulator
Kasbah Nelaria and your investment project
Kasbah Nelaria & Spa is a Darnel Collection project in Marrakech’s Kasbah. The presentation sheet announces ten rooms, approximately 800 m², a spa and a price from €2,000,000. Announced delivery is scheduled for the fourth quarter of 2027. The programme and timeline remain to be checked in the updated dossier.
Its Berber Chic identity draws on natural materials and the landscapes of southern Morocco. The simulation developed in this article illustrates an economic ambition; it does not turn future income into achieved performance.
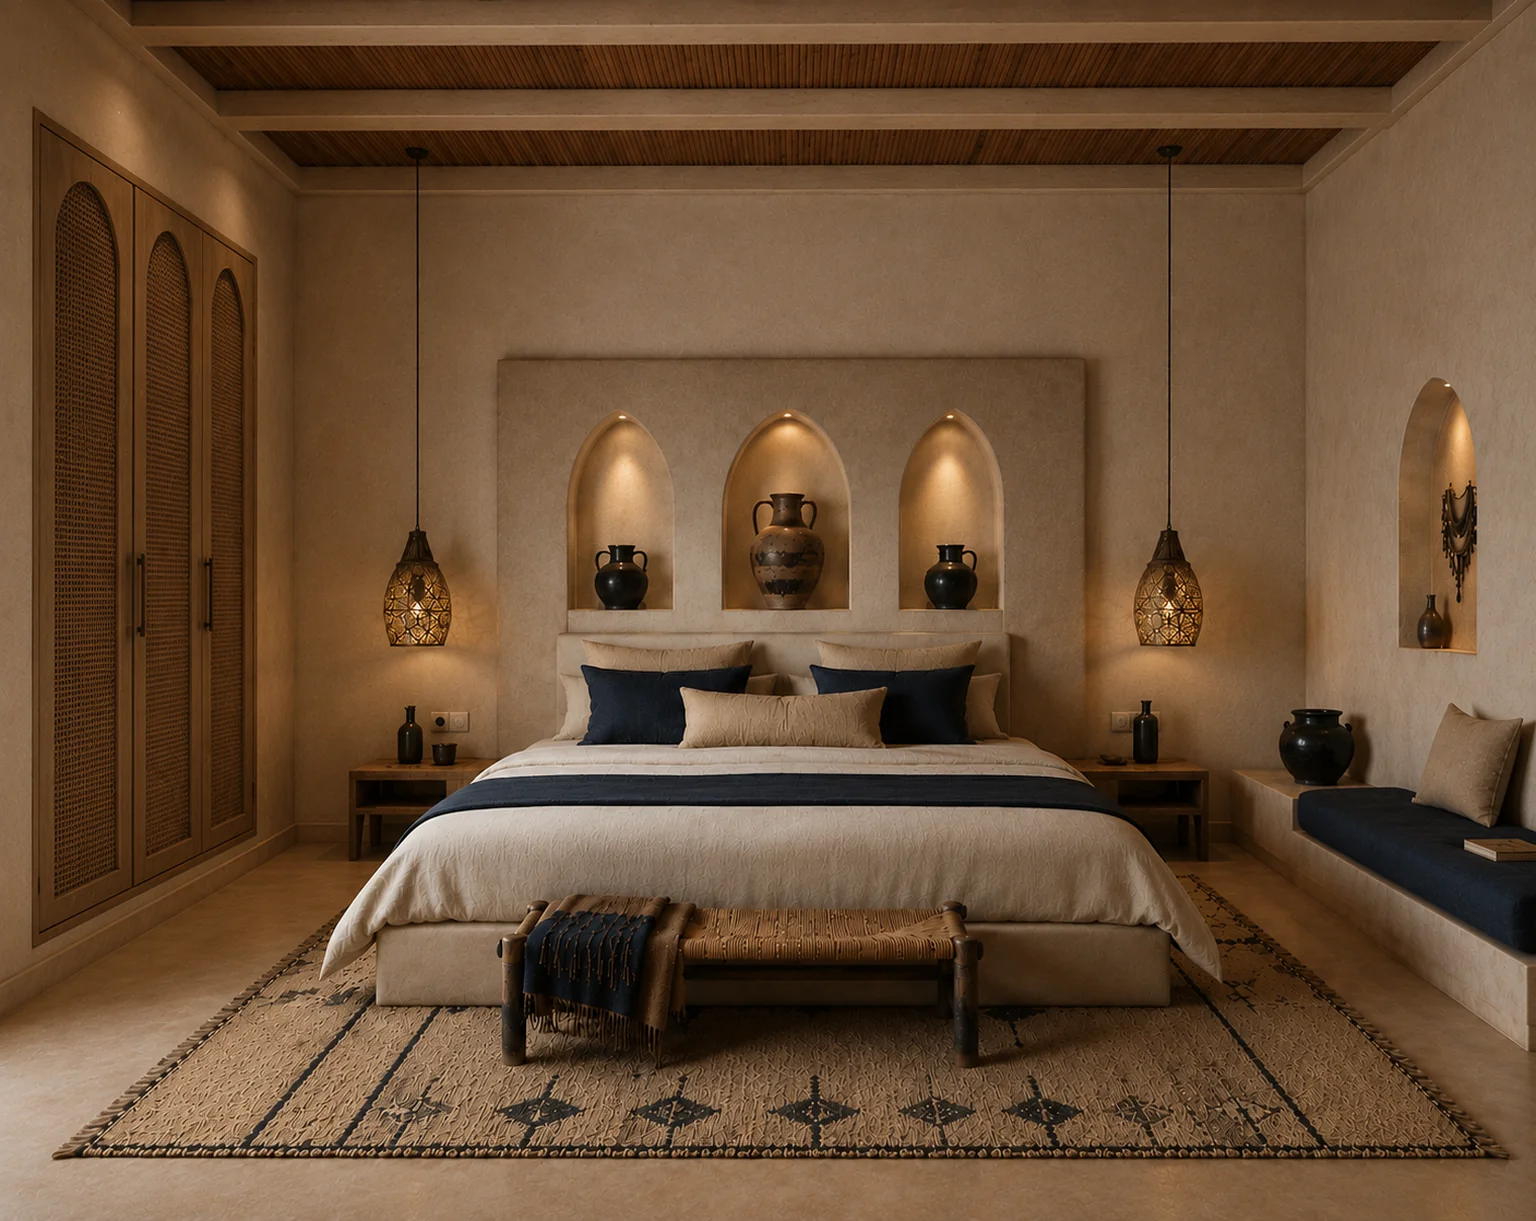
Official architectural rendering of Kasbah Nelaria & Spa — room Aman
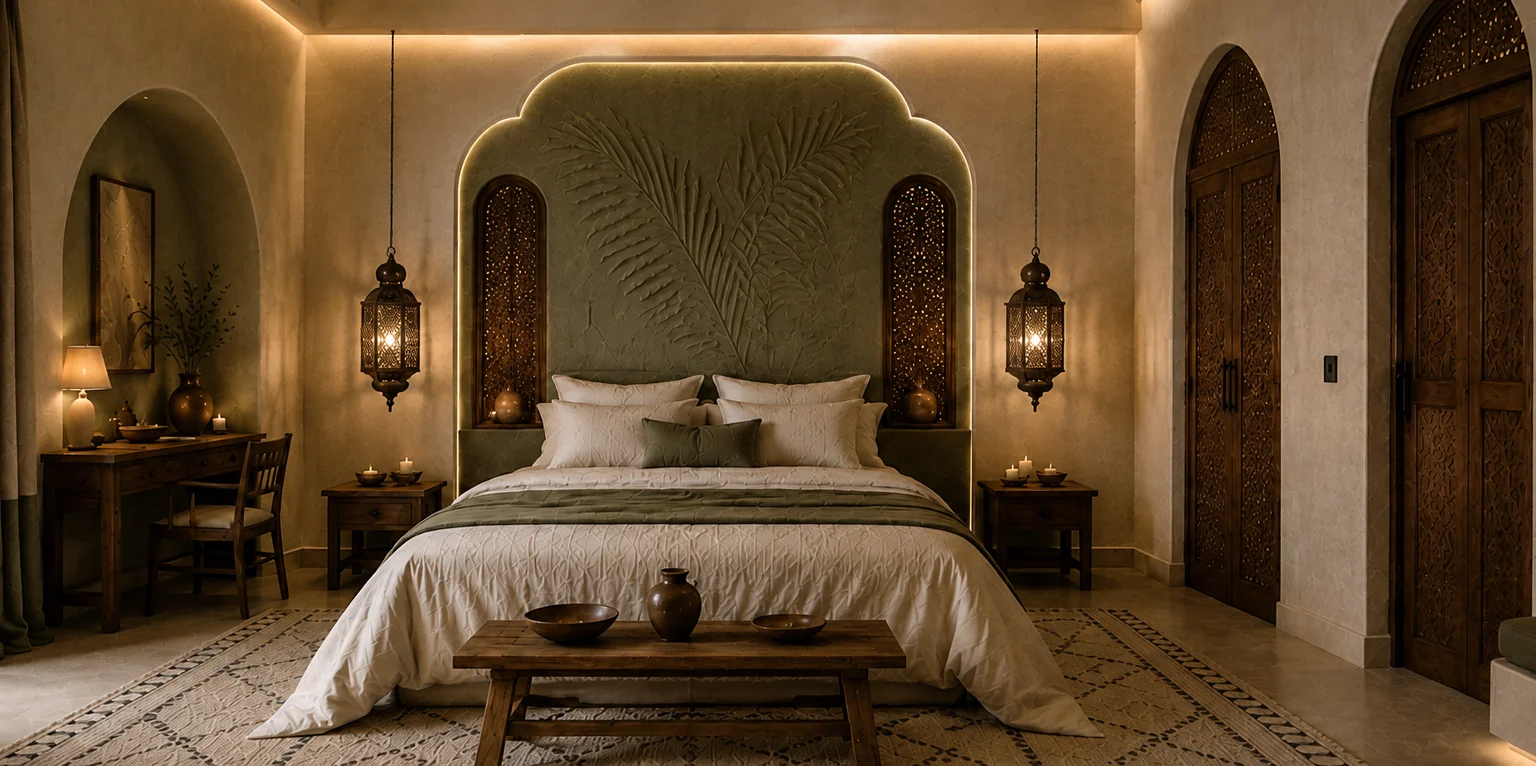
Official architectural rendering of Kasbah Nelaria & Spa — room Tawlit
Request the private presentation of Kasbah Nelaria & Spa
Would you like to compare the capital required, the concept and the conditions for your investment to succeed?
Book a meeting with Darnel Collection to discuss your project
How to organise operations from abroad
An owner based in France or abroad needs local management, clear responsibilities and regular oversight. Darnel Hospitality can support operations: marketing, team organisation, service monitoring and reporting. The choice of manager and their contract must be assessed in the forecast.
Reporting must connect occupancy, ADR, RevPAR, distribution, margins by activity, expenses and cash flow. High occupancy only has economic value if rooms are sold at a price and distribution cost that allow a sufficient contribution.
Frequently asked questions
Can you target more than twenty per cent
The simulation exceeds 20% of the reference price in year 3. It relies on ambitious assumptions and on a balance whose scope must be distinguished from net profit and available cash.
Does the €2,000,000 price include everything
This is the advertised reference price for the project, starting from €2,000,000. The updated dossier must specify inclusions, exclusions and additional fees to establish the total capital required.
Is an ADR of 300 euros assured
No. It is a premium-positioning assumption to be assessed against comparable properties, seasons, services and the rate actually achieved after discounts.
Why develop the spa and restaurant
To enrich the experience and diversify contributions. Space capacity, authorisations and costs must justify the targets used.
Checks before committing
Before a decision, the project must bring together legally verified property ownership, appropriate authorisations, a documented total budget, a competitive study and a forecast that withstands less favourable trading. For ancillary income, ask for the treatment, cover and service volumes needed to achieve the announced margins.
A boutique hotel can combine property value with a hospitality business. For ten suites in Marrakech, the ambition to exceed 20% can only be assessed by connecting total cost, accessible demand, contributions by activity and all expenditure. The investment dossier must demonstrate this consistency.
Book a meeting with Darnel Collection to discuss your investment
Further reading for your study
Investing in a boutique hotel in Marrakech in 2027
Investing in Marrakech in 2027 and building your budget
The twelve hotel profitability indicators
Georges Lelièvre · Darnel Collection
The figures presented are projections. They are neither historical results nor a promise of returns. Any decision must be based on an appropriate legal, technical, commercial and financial study.